

Brigit: Cash Advance & Credit
Brigit
- 4.8
- 41.77K Reviews
- 5.00M
- Downloads
- Free
- Price
Screenshots
Brigit: Cash Advance & Credit Pros and Cons
Pros
- Instant cash advance when needed
- Seamless user interface
- Helps build credit score
- No hidden fees
- Automatic overdraft protection
Cons
- Limited to specific banks
- Monthly membership fee
- Requires access to bank account
- Not a long-term financial solution
- Limited to US residents only
 Analysis by All-app
I think of Brigit less as a household budgeting hub and more as a personal finance tool that may come up when several people share bills or a device. That distinction matters: money apps work best when each person knows whose accounts and decisions are involved. If you are considering it because a rent payment, utility bill, or grocery run falls awkwardly between paydays, Brigit: Cash Advance & Credit is worth examining as one possible short-term aid—not as a substitute for a shared budget or a plan for recurring expenses.
When a shared bill becomes a personal cash-flow problem
Picture two adults splitting household costs. One person handles the electricity bill, while the other transfers their share after payday. If the bill is due first, the person paying may face a temporary gap even though the household’s overall income is sufficient. A finance app that offers an advance can seem useful in that moment, but the important question is not simply whether money can arrive quickly. It is whether the person requesting it has a realistic way to manage the repayment alongside the next round of household costs.
I would treat an advance as a bridge for a specific, time-sensitive expense, not as shared household money by default. The account holder should decide whether to use it, check the terms shown in the app, and make sure the other people involved understand how the repayment could affect the next budget. That small conversation can prevent an awkward surprise when the next rent contribution or grocery payment is due.
Keep account access and responsibility clear
For a shared phone or tablet, I would avoid leaving a financial account open for other household members to browse. A finance app can expose sensitive personal information, and a device used by several people makes it easier to confuse one person’s account activity with another’s. Each adult should use their own account and credentials rather than treating a single login as a household account. I would also sign out when finished on any device that is not exclusively mine and use the device’s ordinary lock settings.
This is particularly important when a household member asks someone else to “just check” an advance or bill alert. It is safer for the account holder to handle the request directly and share only the information needed for planning. That keeps a useful household conversation—such as agreeing who pays a bill—separate from access to someone else’s financial details.
Brigit is developed by Brigit and sits in the personal finance space. It is free to install, but that should not be read as a promise that every service or borrowing option is cost-free. Before accepting any financial offer, I would read the current in-app terms carefully, including any fees, eligibility requirements, repayment timing, and consequences of a missed payment. Those details matter more than the convenience of a quick button tap.
How it fits into day-to-day money decisions
For a practical routine, I would start by using the app to understand my own cash flow, then discuss only the relevant household amounts with anyone who shares expenses. For instance, if I cover a necessary repair before payday, I would note the amount, the bill date, and the expected repayment alongside other upcoming costs. That is more useful than relying on a vague sense that “there should be enough” later. It also makes it easier to decide whether an advance is actually needed or whether moving a non-urgent purchase would solve the shortfall without borrowing.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
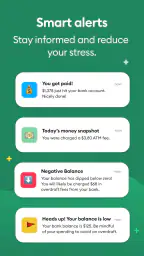
The same approach helps when several bills cluster around the same week. A reminder can prompt me to check the account balance before an automatic payment, but a notification is not a budget and cannot make an unaffordable schedule affordable. I would use alerts as prompts to review, not as a guarantee against overdrafts. If the household routinely has more bills than income, a recurring cash advance may mask the real problem rather than fix it.
Coordinate without turning one person into the household banker
Shared expenses are easier to manage when the household agrees on a simple routine: who pays each bill, when contributions are due, and how an unexpected cost will be handled. Brigit can be part of one person’s own money routine, but I would not assume that it creates a shared ledger or coordinates everyone’s payments. A separate spreadsheet, notes app, or direct conversation may be better for tracking who owes what, especially if several people have different pay schedules.
One useful habit is to decide in advance what counts as an emergency. A necessary prescription or an overdue utility bill may justify considering a short-term bridge; an optional purchase can usually wait. When the need is not urgent, comparing alternatives—such as asking a bill provider about a due-date change, using existing savings, or reducing discretionary spending for that week—can avoid borrowing altogether. The best choice depends on the household’s actual terms and circumstances, so I would compare the total cost and timing rather than assume an advance is automatically the easiest option.
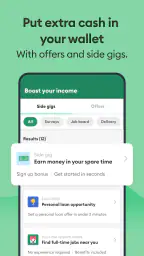
Brigit also presents credit-building and personal-loan options alongside cash-flow tools. Those are different decisions from covering a small timing gap. Before taking on any credit product, I would consider the full repayment obligation and whether it supports a longer-term goal. If I only need help organizing shared bills, a simple budget or a dedicated bill-tracking method may be a better fit than a borrowing-focused app.
Age, trust, and realistic expectations
The app’s content rating is Everyone, but that is not the same thing as saying a financial account is suitable for a child to manage. I would keep financial decisions and account access with the responsible adult, and explain household money choices in an age-appropriate way without handing over credentials. If a teenager needs help learning to budget, a supervised cash allowance or a basic spending plan may be more appropriate than access to an adult’s financial tools.
Trust also means being careful about what a score or alert can tell you. A financial indicator can help organize information, but it is not a complete assessment of someone’s finances and should not be treated as a promise of approval or a measure of personal worth. I would use any guidance as a starting point for reviewing my own habits, then make decisions based on actual balances, due dates, and terms. For a household, that means discussing plans openly while respecting that each adult’s account remains private.
Brigit has an average rating of 4.8 from around 312,000 ratings, and it has been installed over 5 million times. Those figures suggest that many people have tried it, but popularity cannot tell me whether an advance suits my budget or whether its terms work for my situation. It is rated for everyone, was released in April 2018, and version 1043.0 supports Android 8.1 and later. I would still check that my device can run the current version before planning around it.
Who may find it useful—and who may be better served elsewhere
I can see Brigit being most useful for an adult who wants a mobile place to review personal finances and is considering a short-term cash-flow option for a genuine timing mismatch. It may also appeal to someone exploring credit-building or personal-loan tools, provided they are comfortable reviewing financial offers carefully. The app has attracted about 42,000 written reviews, but I would read recent feedback with a practical question in mind: do people describe an experience relevant to my needs, rather than assume their circumstances match mine?
I would skip it if I needed a shared household account, a group bill-splitting system, or a guaranteed way to cover expenses every month. It is also a poor fit if I am not comfortable connecting personal financial information to an app, if I cannot confidently plan for repayment, or if I am looking for a no-borrowing budgeting tool. In those cases, a bank’s own account tools, a paper budget, or a dedicated expense-sharing method may be more appropriate. Usual alternatives differ in an important way: budgeting tools help plan money already available, while credit products create an obligation to repay. I would choose based on which problem I actually have.
The app is free to download, and that makes it easy to explore, but I would not let a zero download price decide whether to borrow. Before requesting any money, I would confirm the amount, timing, fees, repayment method, and what happens if my plans change. I would also check whether the next paycheck has already been allocated to rent, utilities, or other essentials. A quick decision is only helpful if it does not create a harder one a few days later.
For households, my verdict is cautious but practical: Brigit may support one adult’s personal cash-flow decisions, yet it should not become the household’s entire plan for bills or emergencies. Use it privately, discuss shared obligations clearly, and compare borrowing with non-borrowing options first. If the underlying issue is occasional timing, it may be worth considering; if the shortfall repeats, I would focus on a broader budget or speak with creditors about workable due dates instead.
A User-Friendly Financial Companion
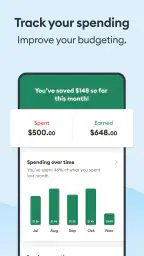
From the moment I installed it, the app's interface was like a breath of fresh air. It’s sleek, easy to navigate, and doesn’t bombard you with unnecessary information. The app categorizes your spending and offers insights, helping you to understand where your money goes each month. It's almost like having a personal financial advisor in your pocket.
Cash Advance Feature
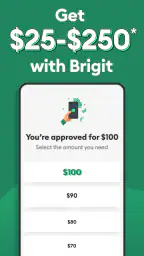
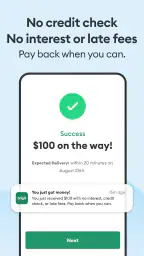
Now, let’s talk about the cash advance feature—the true star of the show. If you’ve ever been caught short before payday, you’ll know how stressful it can be. Brigit offers a quick cash advance to cover those unexpected expenses without the exorbitant fees you’d usually expect from payday loans. Getting an advance is straightforward and, most importantly, fast. You simply request the amount you need, up to $250, and voilà, the money appears in your account. No hidden fees, no interest, just a simple flat fee.
Credit Building Tools
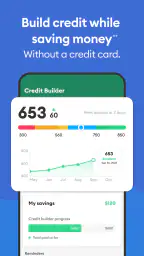
Besides the cash advances, Brigit also offers tools to help build your credit. It provides a nifty feature called Brigit Score, which tracks your financial health. This score is like your credit report card, offering insights and tips on how to improve your financial standing. It’s not just about lending money, it’s about empowering you to make smarter financial decisions.
What I appreciate most is how Brigit sends out alerts to remind you of upcoming bills, helping you avoid those pesky overdraft fees. It's like having a little financial guardian angel on your shoulder, reminding you to pay your bills on time.
Security and Peace of Mind
Security is a big deal when it comes to financial apps, and Brigit doesn’t disappoint. They use bank-level security and encryption to keep your data safe. It’s reassuring to know that your personal and financial information is protected with the same level of security as your bank.
In conclusion, Brigit: Cash Advance & Credit is more than just a cash advance app; it’s a comprehensive tool to help you manage your finances better. Whether you need a quick cash boost or want to build your credit, Brigit simplifies the process and gives you the tools to take control of your financial future. It’s definitely a must-have for anyone looking to improve their financial health. So, are you ready to give it a try and take the first step towards financial freedom?
Frequently Asked Questions
What is Brigit: Cash Advance & Credit and how does it work?
Brigit is a financial app designed to help users manage their finances by providing cash advances and tracking spending habits. Once you connect your bank account, Brigit analyzes your spending patterns and offers up to $250 in cash advances to help you avoid overdraft fees and manage unexpected expenses. The app also provides credit monitoring and budgeting tools to help improve your financial health.
Is Brigit safe to use for managing my financial information?
Yes, Brigit takes security seriously and uses bank-level encryption to protect your financial data. The app does not store your bank login credentials and employs advanced security measures to ensure that your information remains secure. Users can feel confident that their sensitive data is protected while using the app's features, such as cash advances and credit monitoring.
How much does it cost to use Brigit's services?
Brigit offers a free basic plan, which includes financial insights and alerts. However, to access features like cash advances and credit monitoring, you need to subscribe to Brigit Plus, which costs $9.99 per month. This subscription provides access to all premium features, including financial tips, budgeting tools, and faster cash advances.
Can Brigit help improve my credit score?
While Brigit itself does not directly improve your credit score, it provides tools and resources that can help you manage your finances better, which may lead to an improved credit score over time. By helping you avoid overdrafts, manage spending, and offering credit monitoring, Brigit empowers users to make informed financial decisions that can positively impact their credit health.
What are the eligibility requirements for using Brigit?
To use Brigit, you must have a bank account with a checking account that has a history of at least 60 days of activity. Additionally, your account should have a positive balance and display consistent income deposits to qualify for cash advances. Brigit is available to users who meet these requirements, ensuring that they can benefit from the app's financial management tools.


